Venture capital's new public distribution race
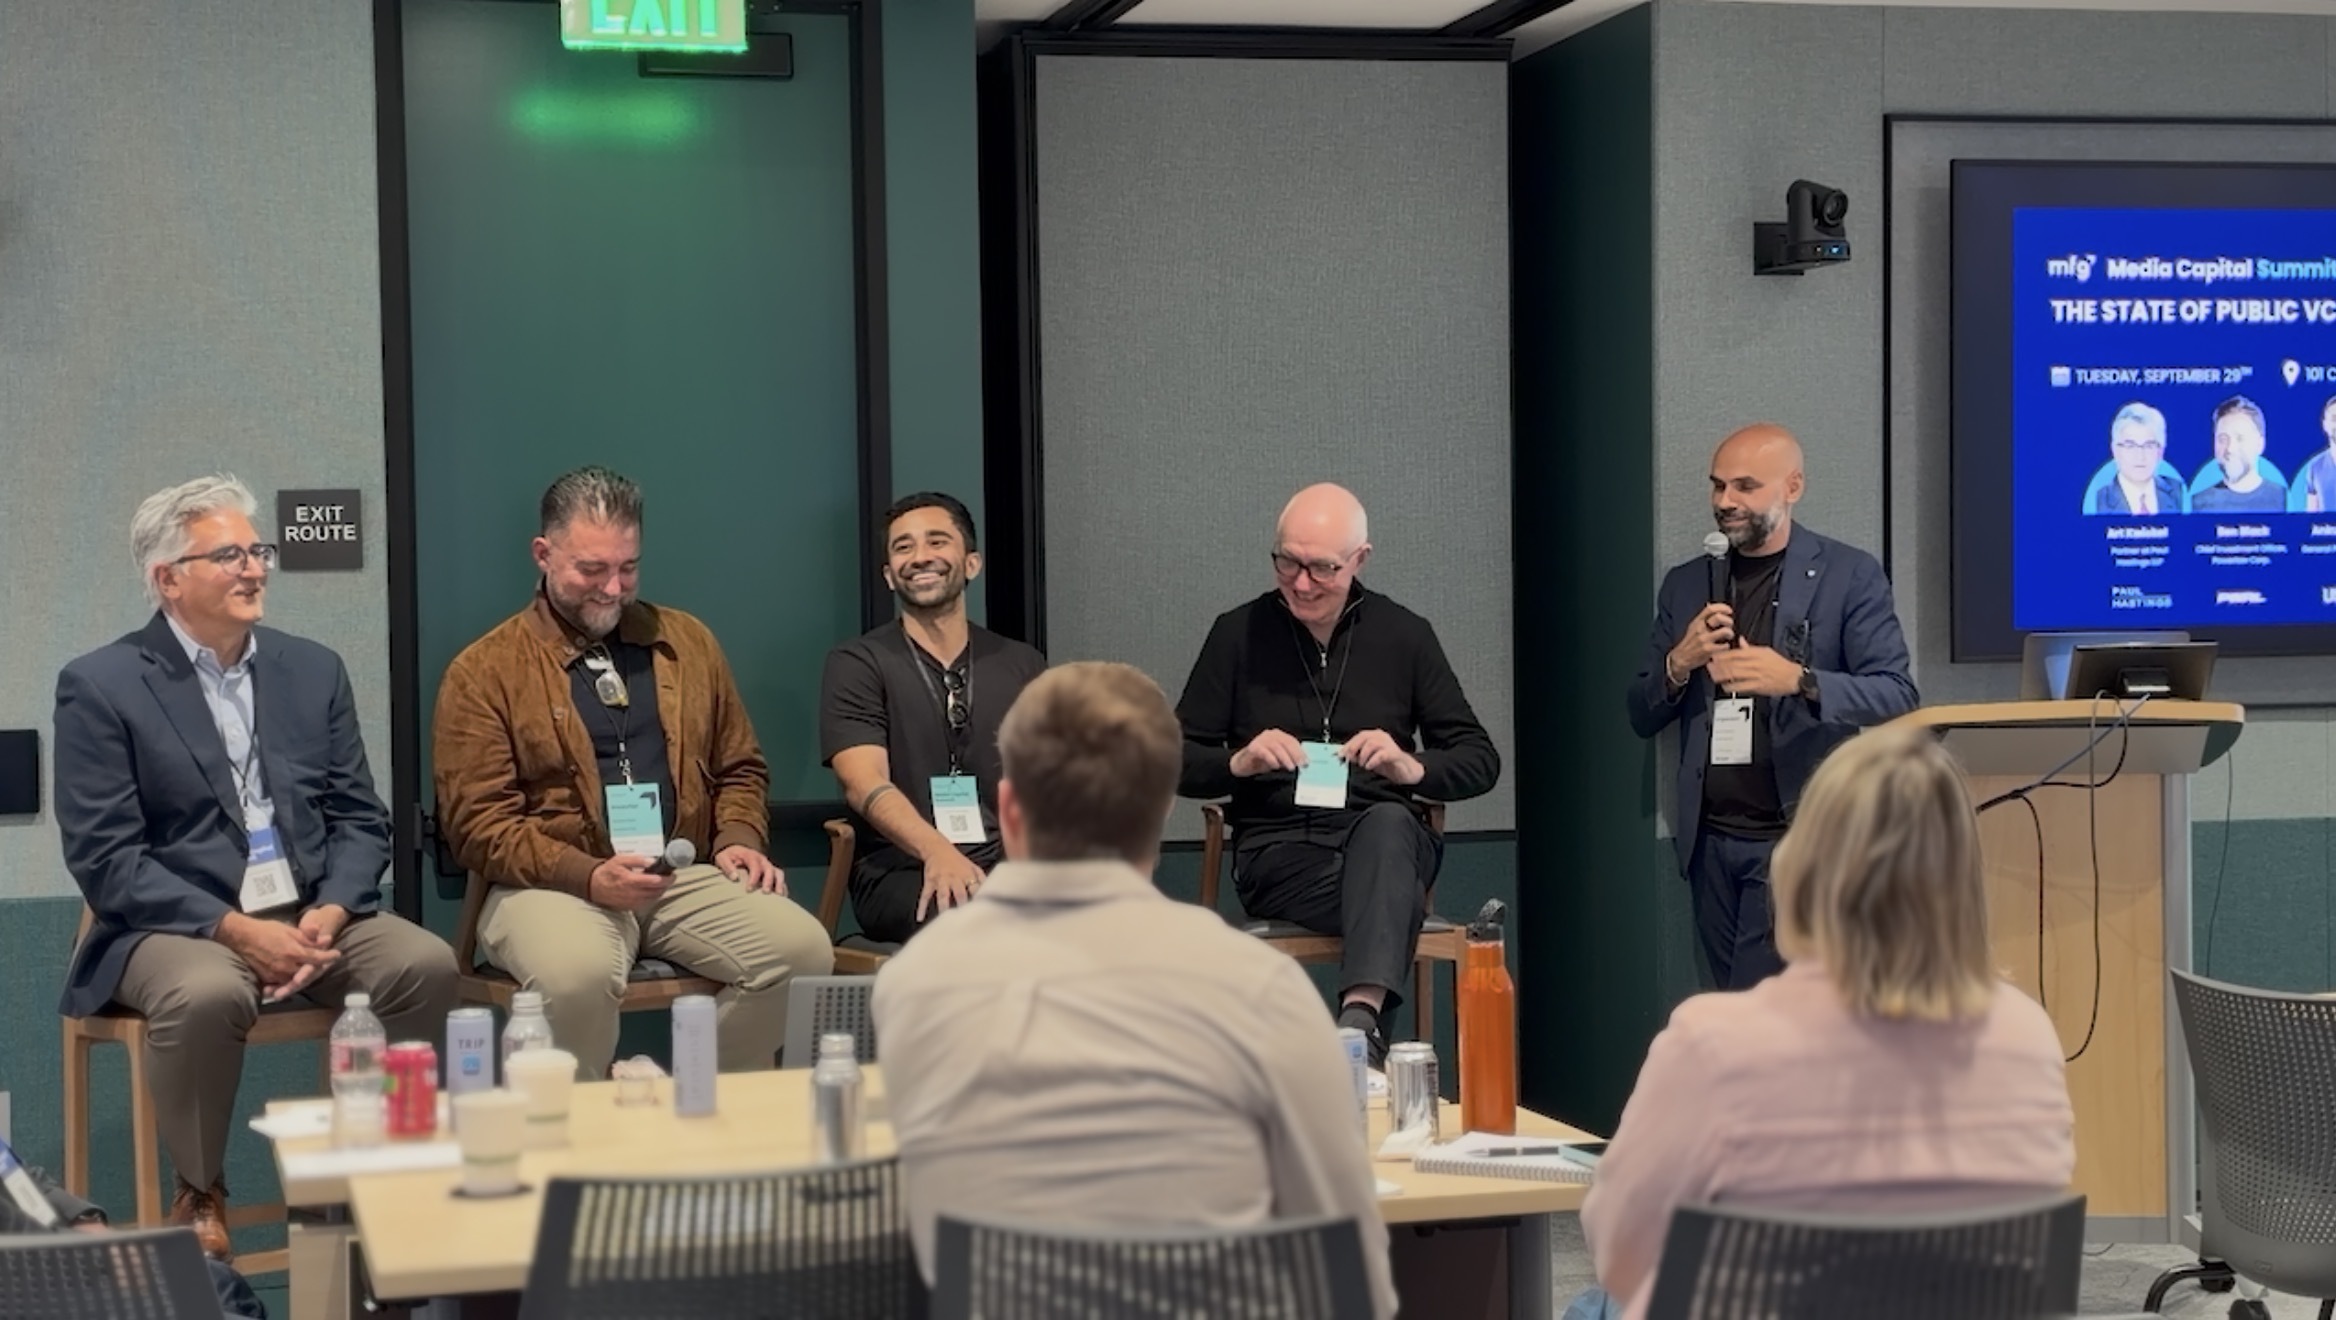
Last month, at our Media Capital Summit in San Francisco, I had the pleasure of exploring the topic of Public VC and the different structures emerging around it alongside Keith Teare (SignalRank), Art Zwickel (Paul Hastings), Ben Black (Akkadian Ventures), and Ankur Nagpal (USVC and Carry). It was a fascinating discussion about how the boundaries between private and public markets are evolving, and what this could mean for the future of venture capital.
When Andreessen Horowitz launched its venture capital firm under the brand A16Z in 2009, it broke venture’s unwritten rule: don’t seek the spotlight.
Marc Andreessen and Ben Horowitz faced a classic cold-start problem. To win the best deals, founders had to view their firm as top-tier; to become top-tier, they needed the best deals. So they manufactured attention before they had the track record, working with PR strategist Margit Wennmachers to orchestrate a highly visible media presence from the outset.
It worked: Being portrayed as the new titans of VC helped them become just that. It also changed the venture playbook.
Wennmachers soon became a partner at the firm, media became a catalyst for their brand, and their brand became a powerful weapon in competing for founders. More importantly, what started with PR at A16Z expanded across the industry. Media became such a powerful tool for VC firms. Fifteen years later, Harry Stebbings, founder and host of the podcast 20VC, turned his media brand into an investment firm.
Over the past 15 years, VC has become a much larger and more widespread industry, while media, storytelling, and brand have become key tools for VC firms competing for founders, deal flow, and investors. This has brought enormous amounts of capital into private markets, enabled companies to stay private for longer, and ultimately created a compelling proposition for public investors who now want a piece of the pie, too.
Why startups are staying private longer
For most of this evolution, the objective was deal flow. But as venture became a larger, more visible industry, it also attracted enormous amounts of capital. Private markets deepened, and a larger shift followed, one that would eventually change not just how firms compete for founders, but who gets to participate in venture capital at all. IPOs used to be a necessity, not a choice: companies went public because private markets simply didn’t have enough capital to fund their growth. That’s no longer true.
Private capital is now deep enough to fund businesses through milestones that once required an IPO, allowing companies to stay private much longer. Consider this: In 1997, Amazon was listed at a $430 million valuation. In comparison, SpaceX reached a $1.77 trillion valuation before listing, almost 4,000 times larger than Amazon.
As companies stay private for longer and more value creation remains behind private walls, broader demand for access has followed, and venture has started opening to non-institutional investors.
The rise of public VC
Public VC is emerging as a new category of investment vehicles that give ordinary investors diversified exposure to portfolios of private venture-backed companies, either through publicly listed funds or evergreen structures offering periodic liquidity.
The Destiny Tech100 fund, listed on the NYSE in 2024, gave ordinary investors access to private giants including SpaceX and OpenAI. In March 2026, Fundrise took its venture fund public, and Robinhood listed Robinhood Ventures Fund I on the NYSE at $25 a share. Later, AngelList introduced USVC, an evergreen fund accessible to non-accredited investors for a $500 minimum investment.
Why past attempts at access fell short
Previous attempts to broaden private-market access haven’t lived up to their initial promises. Equity crowdfunding opened startups to retail investors but suffered from adverse selection, illiquidity, and lack of curation. Later, platforms like Moonfare and Titanbay gave wealthy individuals access to professionally managed private funds, improving curation but hitting another wall: acquiring and educating individual investors in a complex, high-consequence category like venture capital is expensive. Because of this, most of these companies shifted toward selling through other businesses, like financial advisors, instead of scaling their proposition directly to individual investors.
Access wasn’t enough. Curation wasn’t enough. Distribution remained the barrier.
An exchange can give a fund manager a ticker, but that alone won’t attract investors or bring in an audience. And it won’t turn a firm built to serve big institutions into one that knows how to serve everyday public investors.Public VC requires capabilities traditional VC rarely needs, such as managing continuous secondary trading, Net Asset Value premia and discounts, liquidity, public disclosures, education, and investor relations at scale.
Media becomes the new advantage
This is where VC media operations look more consequential today. Over the last decade, some firms built podcasts, publications, and communities, largely to attract founders and support portfolios. In the process, they have built infrastructure for something bigger.
Of the four public VCs cited above, all had an unfair advantage: Destiny was the first to launch this type of fund; Robinhood had the brokerage app and massive retail user base; Fundrise had a community with years of private-market investing behavior; and AngelList had the network and platform.
Media-led venture firms, like A16Z and 20VC, already have an audience. VCs that want to appeal to the public, and lack an audience, must manufacture their own distribution. That means manufacturing public awareness.
My business partner, Luca Zaccagnino, experienced a similar dynamic firsthand. Earlier in his career, he created structured products for distribution through banking networks. When the 2008 financial crisis closed those channels to third-party issuers, his business lost its path to clients. The business pivoted using public exchanges as the alternative rail, while PR, investor education, and media aimed to generate consumer demand. Without a retail branch network, and despite resistance from incumbent intermediaries, the firm distributed over 3 billion euros in notes; multiples of its historical sales. Surprisingly, bypassing bank gatekeepers didn’t hurt Royal Bank of Scotland’s institutional standing: national brand visibility strengthened its profile across all channels.
The exchange provided a way to transact directly with investors. Media and education created the demand. And the brand lift traveled far beyond the product that was advertised.
I see similar opportunities emerging in venture, with an even stronger flywheel: media builds the VC brand; brand attracts capital and top founders; founders leverage the investor’s brand and reach to attract customers, talent, and further capital; successful companies strengthen the investor’s brand, attracting the next generation of founders and capital.
As a case in point, Fundrise’s CEO Ben Miller explained that while investing in Loyal, a longevity startup for dogs, he saw the opportunity to introduce the company to Fundrise’s 2 million clients, including hundreds of thousands of dog owners and thousands of veterinarians. He called this network investing. For consumer-facing and pre-IPO companies, an investor’s public reach can become a commercial asset as well as a financial one.
It is harder for founders to ignore a public VC that becomes a household name.
What still needs to be solved
Public VC remains far from its finished form. Listed vehicles move the liquidity problem into market prices, potentially trading at wide premia or discounts to Net Asset Value. Interval funds must maintain liquidity reserves and cap redemptions. Average annual costs hover around 3.5%, well above traditional VC’s 2%, and while the absence of carried interest reduces performance-related costs, it can also shift manager incentives toward Assets Under Management accumulation over performance.
Yet the category has huge potential. Its wrapper, economics, portfolio construction, and distribution models are still evolving. New financial products do not emerge fully formed. Structures improve, fees compress, and markets adapt.
Allocating 5% of any investor’s portfolio to public VC may become standard, Miller said, and that would allow everyday investors to participate in private value creation before transformational companies reach multi-hundred-billion-dollar public valuations.
Until then, the competition for the audience is wide open.
Relationships created access in venture’s first era. Brand defined its second era. Now, in the third era, media and an audience could turn the investor’s brand into distribution, and distribution into a decisive advantage to win in both races, for capital and for the best deals.
Written by Luca Zaccagino, Partner at mediaforgrowth